Reflects trade-payment behavior reported across Reklaim Credit Solutions’ contributory network, giving your team context beyond its own ledger.
Predictive Credit Report
Cannabis Credit Report Built for Better Credit Decisions
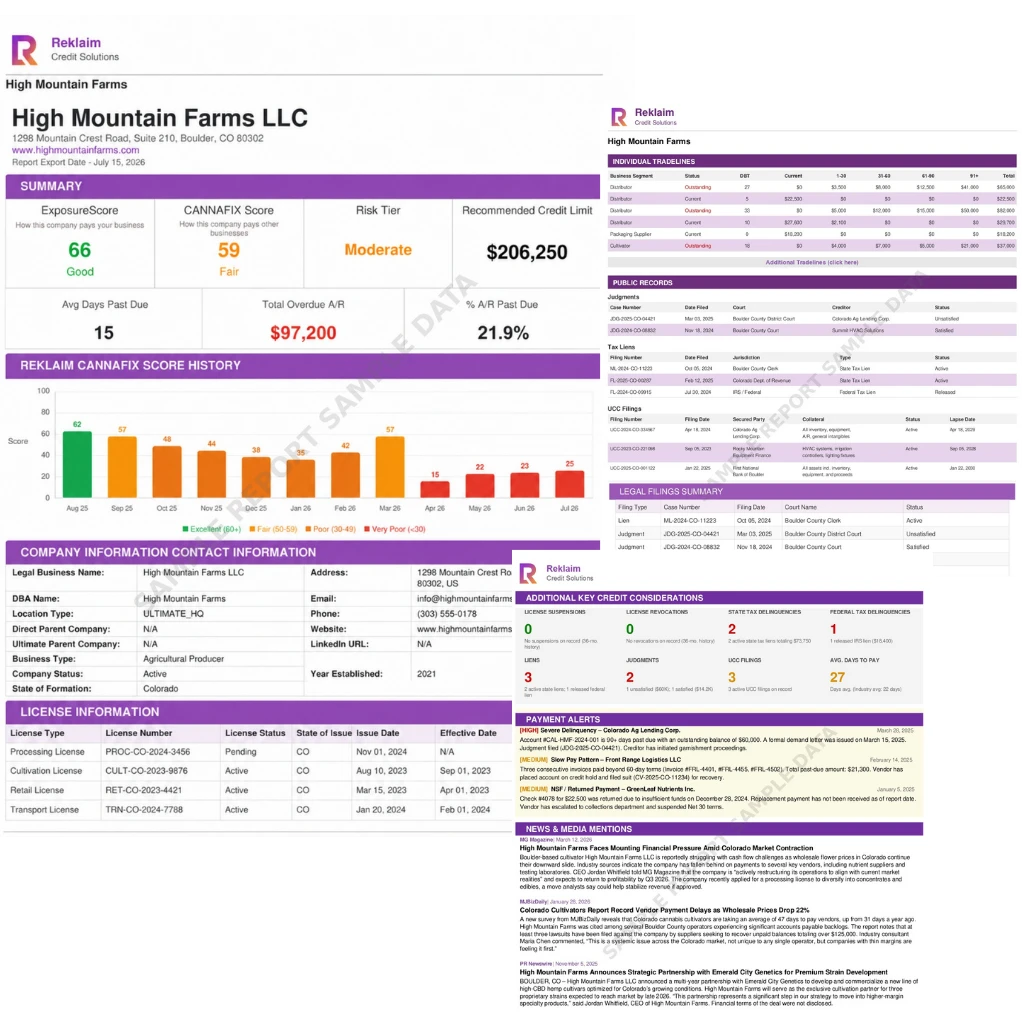
Before you extend terms, increase a credit line, or release another order, know who you are dealing with. See payment history, CANNAFIX Score, recommended limits, tradelines, licenses, public records, and credit concerns in one industry-built report.
What is a cannabis credit report?
The questions a credit manager actually needs answered.
01
Does this company pay its suppliers?
02
How late does it pay?
03
Is payment behavior improving or getting worse?
04
Are there liens, judgments, or license problems?
05
How much credit should we extend?
A cannabis credit report evaluates a cannabis company before extending trade credit or increasing an existing credit line.
Reklaim Credit Solutions brings the answers together around how cannabis businesses buy and sell on terms—without relying on personal credit.
Before you extend credit
Know who you’re extending it to.
A new customer wants Net 30. Sales wants the order released. Their references check out.
That still doesn’t show how the company pays the rest of the market. Reklaim Credit Solutions puts your A/R experience, contributed payment data, and public information into a broader credit picture.
At a glance
Get to the credit question first.
Start with the decision. Then go deeper into the information behind it.
01
CANNAFIX Score
Current credit rating based on payment behavior across the Reklaim Credit Solutions network.
02
Risk Tier
Put the score into the context your credit team needs for review.
03
Recommended Credit Limit
See the trade exposure supported by the current credit profile.
04
Average Days Past Due
Understand how far beyond terms the company is paying.
05
Total Overdue A/R
See the reported receivables already past due.
06
Percentage of A/R Past Due
Understand how much has moved outside agreed terms.
Inside the report
Ten sections. One credit file.
Built to take a credit manager from the initial review through the details behind the decision.
01
Credit Summary
Score, risk tier, recommended credit limit, average days past due, and overdue receivables.
02
Score History
See whether the CANNAFIX Score is improving, holding steady, or deteriorating.
03
Company Information
Confirm the legal entity, DBA, parent structure, business type, and state of formation.
04
License Information
Review available license status, issue dates, and expiration dates.
05
Tradelines
You can see the ExposureScore and Average Days Past Due for each of the members of the network who are selling an individual company.
06
ExposureScore
See supplier relationships and receivables aging from current through 90+ days past due.
07
Public Records
Review suits, judgments, tax liens, UCC filings, and mechanics liens.
08
Key Credit Considerations
Bring license issues, tax delinquencies, and changing payment performance forward.
09
Payment Alerts
Watch for slow pay, serious delinquency, returned payments, and material credit events.
10
News & Media
Keep relevant company developments alongside the credit file for context.
Trade-payment history
See how the customer actually pays.
Revenue does not pay your invoices. Customers do.
A business can keep ordering and look healthy while supplier payments stretch from 30 days to 45, then 60, then 90. Reklaim Credit Solutions uses contributed A/R aging to show how obligations are being handled across reported relationships.
Current balances
Past-due balances
Aging movement
Average days past due
Payment trend
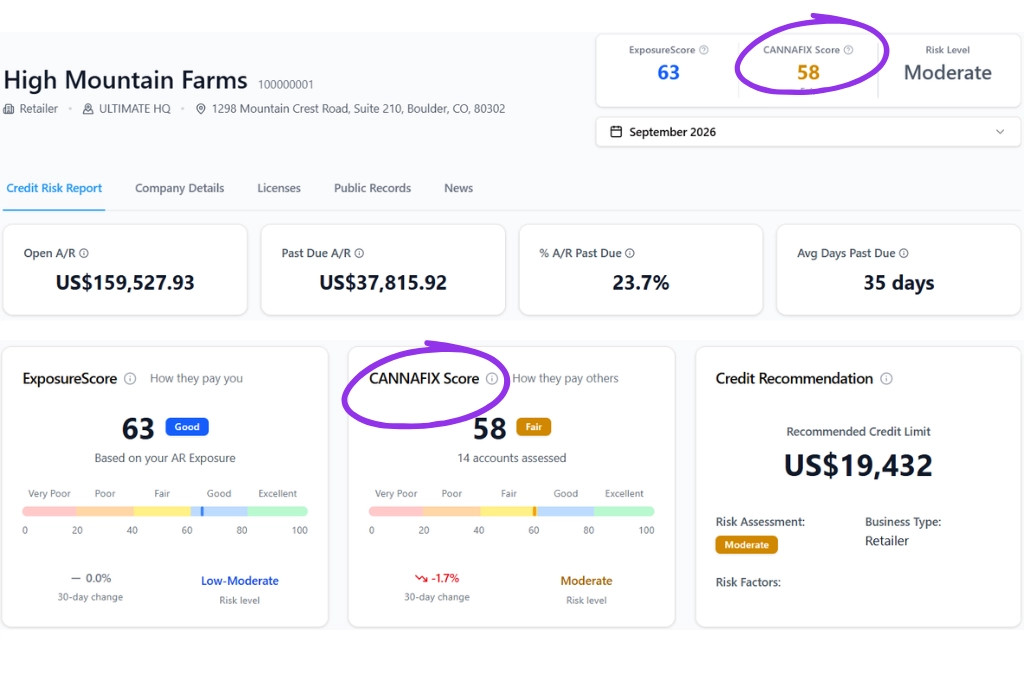
Two proprietary scores
How they pay the market. How they pay you.
Those are two different questions. Looking at one relationship without the other can lead to the wrong conclusion.
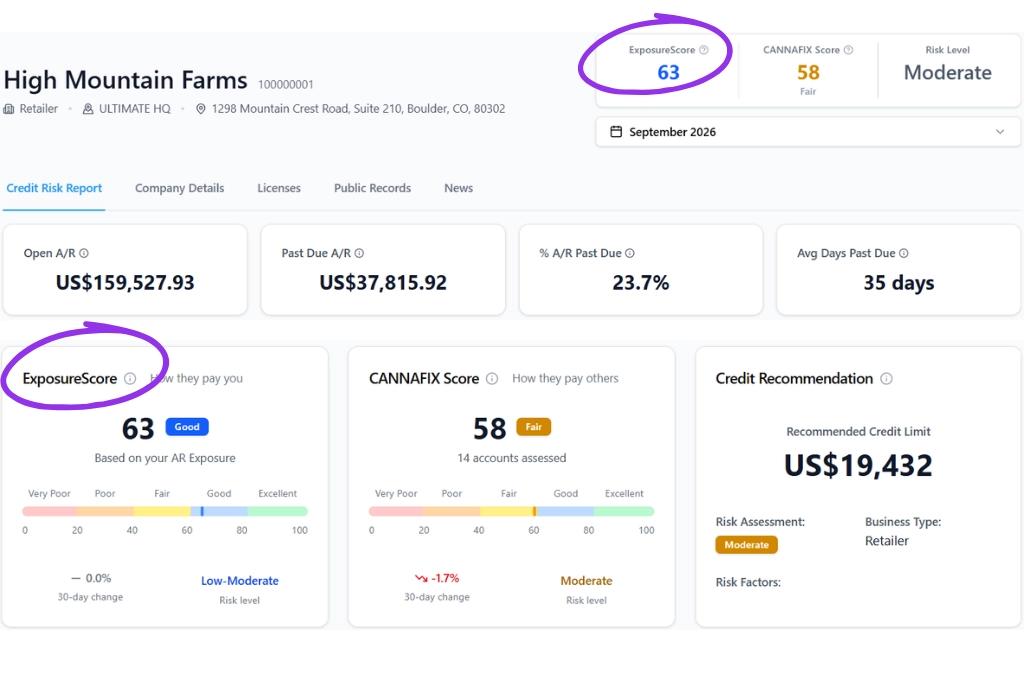
Reklaim ExposureScore
Based on the customer’s payment performance in your own A/R. Compare your direct experience with the broader market.
When the two scores begin telling different stories, that is worth investigating.
Recommended credit limit
“Approved” is only half the credit decision.
How much are we willing to have outstanding at one time?
A score says something about risk. A recommended limit turns that information into a decision your team can put into policy.
- Approve the requested terms
- Set a lower starting limit
- Increase or reduce an existing limit
- Tighten terms
- Move the account to COD
- Pause additional shipments
Public records & licenses
Payment history is not the whole credit file.
A filing does not automatically mean you stop doing business. It means the decision deserves context.
Public records
Suits, judgments, tax liens, UCC filings, and mechanics liens.
Cannabis licenses
License type, status, issue date, and expiration date.
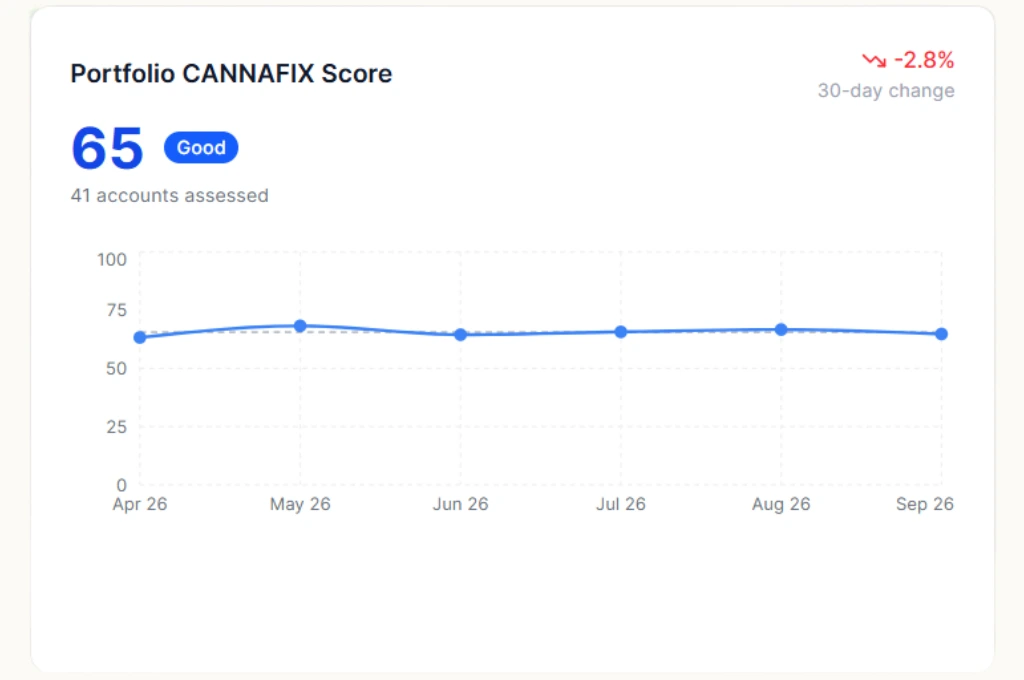
Not a one-time credit check
Credit risk changes after the account is open.
Cash gets tighter. Payments slow. A tax lien appears. A license lapses. Reklaim Credit Solutions tracks score movement so you can see whether risk is improving, stable, or moving in the wrong direction.
A score gives you the current position. The trend gives you the part that deserves attention.
Where the information comes from
Built from the way cannabis companies actually pay.
Participating companies securely contribute de-identified A/R aging. Customer lists, pricing, and trade terms are not shared with other members.
01
Contribute
Send monthly A/R aging through supported accounting systems or CSV.
02
Score
Compare payment behavior across reported relationships, not just one supplier.
03
Review
Use scores, trends, limits, records, and licenses to make the decision.
Throughout the customer relationship
Use the report whenever the risk you carry may change.
01
New customer review
Pull the report before approving Net 30 and review payment behavior, rating, limit, licenses, and records.
02
Credit approval
Choose open terms, tighter terms, a lower initial limit, or COD—and document why.
03
Set the credit limit
Establish the maximum exposure your company is prepared to carry.
04
Release orders
Check whether the account still supports a shipment that materially increases exposure.
05
Review existing customers
Revisit accounts when scores decline, payment patterns change, or exposure increases.
06
Adjust early
Reduce limits, tighten terms, hold an order, move to COD, or start the collection conversation sooner.
Good credit management does not mean saying no to every risky account. It means knowing the risk before you say yes.
Who uses Reklaim Credit Reports?
Built for businesses that extend trade credit in cannabis.
Cultivators & brands
Set exposure before product leaves your control.
Distributors & wholesalers
Manage credit across a large book of retail accounts.
Vendors & service providers
Check the business before giving it 30, 45, or 60 days.
Lenders & institutions
Add cannabis trade-payment intelligence to underwriting.
The complete credit picture
Stop making a large decision from one piece of the file.
Your A/R aging
How the customer pays you—not the wider market.
Trade references
Selected relationships—not always the full pattern.
Public records
Material filings—not ordinary payment behavior.
License records
Regulatory status—not whether invoices are paid on time.
The Reklaim Credit Solutions' Credit Report brings it all together
- Trade-payment behavior
- CANNAFIX Score
- ExposureScore
- Score history
- Credit limit
- Tradelines
- Public records
- License information
- Alerts
Frequently asked questions
Cannabis Credit Report FAQs
What is a cannabis credit report?
A commercial credit report used to evaluate the creditworthiness of a cannabis business. It can include trade-payment history, ratings, aging, tradelines, public records, licenses, limits, and other information relevant to extending business credit.
What information is included in a Reklaim Credit Report?
Nine sections cover the credit summary, score history, company information, cannabis licenses, tradelines and ExposureScore, public records, key credit considerations, payment alerts, and relevant news and media.
How do I check the credit of a cannabis business?
Identify the legal business, then use its Reklaim report to review trade-payment history, CANNAFIX Score, recommended credit limit, public records, licenses, and other available credit information.
Can I check a dispensary before extending Net 30 terms?
Yes. Review the business, payment information, score, recommended limit, license status, and available public records before creating a material balance.
What is the difference between a credit report and a credit score?
The CANNAFIX Score summarizes credit risk on a 0–100 scale. The full report provides the supporting payment history, trend, recommended limit, tradelines, records, licenses, and other considerations.
What is a tradeline in a commercial credit report?
A tradeline represents a reported commercial credit relationship. Multiple tradelines provide a broader view than a single supplier reference.
Does the report show how late a company pays?
Yes. Average days past due and receivables aging help distinguish accounts that pay within terms from balances moving into older aging periods.
Does the report include liens, judgments, and license information?
Available information can include suits, judgments, tax liens, UCC filings, mechanics liens, and cannabis license type, status, issue date, and expiration date.
How often can a company's credit risk change?
At any time. Reklaim recalculates scores monthly as new A/R information becomes available, helping teams see movement rather than relying on a one-time check.
Can I use a Reklaim Credit Report on an existing customer?
Yes. Use it when reviewing an account, considering a limit increase, investigating slower payments, releasing a large order, or reassessing terms.
Reklaim Credit Solutions
Know who you’re extending credit to.
Know how the customer pays, understand what changed, set a limit you can defend, and decide before another invoice lands in A/R.