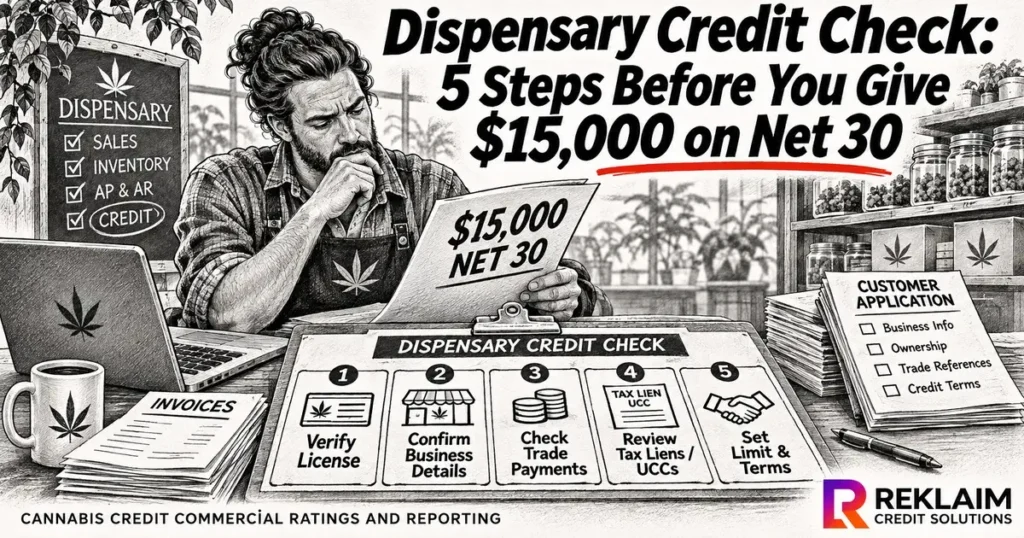
When you ship $15,000 worth of product to a dispensary on Net 30 terms, you’re putting $15,000 of your company’s money at risk. The customer gets the inventory immediately, while you finance it interest-free, usually without collateral or a guarantee of payment.
If the invoice stretches to 60 or 90 days, your exposure continues, and each additional shipment can increase what you stand to lose.
No bank would make a $15,000 unsecured business loan without investigating the borrower’s financial condition, reviewing its payment history, and establishing a credit limit. Yet many cannabis suppliers extend similar amounts based on relationships, purchase history, or a salesperson’s confidence in the customer.
Extending credit is often necessary to compete in cannabis, but extending it without understanding the risk isn’t. Before your next shipment, take these five steps to protect your company.
What Should You Check Before Offering Net 30 to a Dispensary?
A dispensary credit check should answer five questions before product leaves your warehouse. Here are the five areas to review before deciding whether to approve terms and how much credit to extend.
1. Require a Completed Cannabis Credit Application
Credit applications are standard practice in most B2B industries, and cannabis should be no different. When a customer asks for thousands of dollars in unsecured credit, requiring a completed credit application should be a basic part of doing business.
A credit application provides important information about the business, including its legal name, ownership, banking relationships, and trade references. It can also establish contractual terms addressing collection expenses, attorney fees, interest on overdue balances, and personal guarantees, depending on how it’s drafted and applicable law.
There’s also something to learn from how a prospective customer responds to the application process. If a business wants $15,000 in unsecured credit but refuses to provide basic information, you should consider why it’s unwilling to answer questions any commercial lender would ask.
A refusal doesn’t automatically mean the customer is a bad credit risk, but it warrants further investigation. Establish the terms of your credit relationship before the first shipment, not after the customer stops paying.
2. Verify the Dispensary License and Monitor Its Status
Cannabis businesses face regulatory risks that most traditional businesses don’t, and maintaining an active state-issued license is essential to their operations. A dispensary that loses its license may be unable to generate the revenue needed to pay suppliers.
Before extending credit, verify the license directly through the appropriate state regulatory authority rather than relying on the customer’s assurances. Confirm that it belongs to the correct legal entity and location, is active, and isn’t approaching an expiration or renewal deadline.
License verification shouldn’t end with the initial credit approval because regulatory circumstances can change. A business that was properly licensed when you opened the account could encounter compliance problems, suspension proceedings, or renewal issues months later.
If you’ve extended $15,000 in credit and the dispensary suddenly loses its ability to sell cannabis legally, collecting that receivable becomes considerably more difficult. Monitoring license status gives you an opportunity to reassess the account before additional shipments increase your exposure.
3. Review How the Dispensary Pays Its Bills
Banking remains challenging for cannabis businesses, but that doesn’t eliminate the need for sound financial management. Before extending credit, understand how the dispensary manages its cash, pays its bills, and prioritizes financial obligations.
Ask who handles accounts payable, whether the business follows a regular payment schedule, and how management forecasts upcoming expenses. You don’t need access to every banking detail, but you should understand whether the company has a reasonable process for meeting its obligations.
A dispensary can have strong sales and still experience cash-flow problems. Rent, payroll, taxes, inventory purchases, and expansion costs all compete for the dollars suppliers expect to receive.
If management can clearly explain how bills are processed and vendors are paid, that’s useful information. If nobody can give you a straightforward answer, that tells you something too.
4. Match the Credit Limit to the Owner’s Track Record
Experience matters when evaluating commercial credit risk, particularly in an industry as complicated as cannabis. Someone who has successfully operated several dispensaries brings a different level of experience than someone opening their first location.
Cannabis retail requires owners to manage inventory, compliance, staffing, purchasing, taxes, and cash flow simultaneously. A first-time operator may be learning these responsibilities while establishing a customer base and competing with established dispensaries.
That doesn’t make a first-time owner a bad credit risk, but it does make the business an unproven one. Rather than immediately extending $15,000 or $25,000 in credit, consider starting with a smaller limit and increasing it as the customer establishes a reliable payment record.
Credit limits should reflect the customer’s demonstrated ability to pay and your willingness to assume risk, not simply the size of the order your salesperson wants to close.
5. Check How the Dispensary Pays Other Cannabis Suppliers
This may be the most important step of all, and it’s the one your own accounts receivable aging report can’t do for you. A dispensary can be paying you consistently within terms while falling 60, 90, or even 120 days behind with other suppliers.
Imagine a dispensary you’ve supplied for two years that has always paid within 30 days. Your salesperson considers it an excellent account, management knows the owner personally, and nothing in your aging suggests there’s a problem.
What you can’t see in your own receivables is that the same dispensary may be stretching several other suppliers, carrying an outstanding tax lien, or facing lawsuits over unpaid invoices. By the time those problems affect payments to you, the warning signs may have been there for months.
When cash becomes tight, retailers often prioritize suppliers whose products they need most. Being an important supplier doesn’t necessarily protect you; it may simply mean you’re among the last creditors to experience the problem.
Checking trade references and reviewing industry-specific credit reports can reveal information your accounting system cannot provide. Payment behavior across suppliers, legal filings, tax liens, and changing credit scores can help identify problems before they reach your ledger.
That’s the gap we built Reklaim Credit Solutions to help close in cannabis, combining payment data contributed by participating suppliers with public records and license information
Why Should You Monitor a Dispensary After Credit Approval?
One mistake suppliers make is treating credit approval as a permanent decision. A customer might receive a $15,000 limit when the relationship begins, and that limit can remain unchanged for years even as its financial circumstances deteriorate.
Payment patterns slow, balances grow, tax problems emerge, and management teams change. Monitoring these developments helps determine whether current limits and terms remain appropriate or whether exposure should be reduced.
Net 30 is a loan, whether you think of it that way or not. Know who you’re extending credit to, understand how they pay their bills, and keep monitoring the risk after the sale.